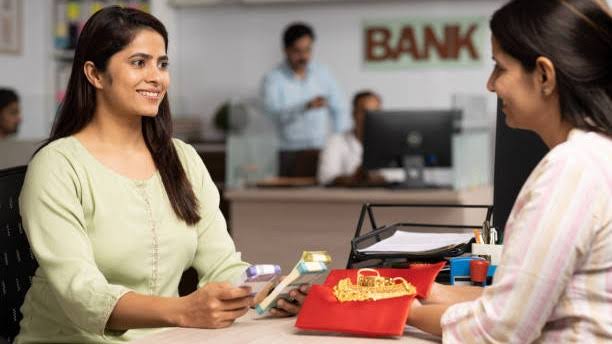
For generations, gold jewellery in Indian households has often been associated with women, even when financial decisions were recorded in a man’s name. More women are now appearing as the primary borrower when family jewellery is pledged for credit. The shift doesn’t have a single cause. Greater participation in paid work, wider ownership of small businesses, better access to formal finance and clearer recognition of women’s rights over jewellery all play a part. Digital access has also made it easier to compare lenders and understand repayment obligations. Yet being named first is more than an administrative detail. It places the borrower at the centre of the contract, with direct responsibility for disclosures, repayments, notices and the eventual release of the pledged ornaments.
Why are more women borrowing in their own names?
Women increasingly manage household cash flows, operate shops, provide professional services and run home-based enterprises. When a short-term funding gap arises, applying for a gold loan may be more practical in their own name than routing the transaction through a spouse or another relative. Jewellery received as a gift, inheritance or streedhan may also belong to the woman, making her the natural person to pledge it, subject to the lender’s verification process.
The change is visible across several everyday situations:
- A retailer needs stock before a festive sales period.
- A salaried borrower must meet an unexpected family expense.
- A self-employed professional requires temporary working capital.
- A household wants the person who owns the jewellery to control its release.
How digital access is changing borrower participation
Earlier, a branch visit could involve paperwork, travel and dependence on another family member. Today, a gold loan app may allow a prospective borrower to review basic information, initiate an enquiry, track an account or make payments, depending on the services offered. Digital channels don’t remove appraisal, identity checks or other regulatory steps, but they can give women more direct access to information and account records.
A gold loan calculator can provide an indicative view of interest or repayment amounts based on selected inputs. The final sanction may differ after purity testing, net-weight assessment, valuation and application of the permitted loan-to-value ratio. Still, the ability to examine scenarios privately helps a borrower enter the discussion with better questions.
Does being the primary borrower improve financial control?
It can, although it also creates obligations. The primary borrower typically receives the sanction terms, pledge receipt, account communications, repayment reminders and notices connected with the collateral. This direct line of communication may give a woman greater visibility over the outstanding amount and the conditions for retrieving her jewellery. It may also build a formal credit record when repayment performance is reported to credit information companies, as per applicable norms.
However, the borrower should examine the full cost rather than focus only on the advertised gold loan interest rate. Processing fees, valuation charges, penal charges, renewal terms and auction-related provisions may affect the total amount payable. Before signing, she should confirm:
- Whose name appears on the pledge and receipts
- How the jewellery’s purity and net weight are recorded
- Which repayment structure applies
- How notices will be delivered
- What process follows after full repayment
What protections and responsibilities matter?
Fair lending principles apply regardless of gender. Regulated lenders are generally expected to provide transparent terms, document the pledged ornaments, explain charges and follow prescribed procedures for custody, release and, where necessary, auction. Under the RBI’s 2026 framework for lending against gold and silver collateral, lenders must follow applicable requirements on valuation, loan-to-value limits, documentation, collateral handling and borrower communication. Implementation details may depend on the lender, product and regulatory timeline.
A woman should not be named as the borrower simply to satisfy an internal sales target or because the jewellery is assumed to be hers. Consent, ownership declarations, repayment capacity and KYC information must be genuine. Family members may assist, but the named borrower remains responsible for understanding the agreement. Lenders, in turn, should communicate directly and avoid allowing relatives to override her instructions without valid authority.
Conclusion
The growing presence of women as primary borrowers reflects a broader shift in financial agency. Women are earning, running enterprises, managing family budgets and asserting clearer control over assets linked to them. Digital tools and more formal documentation have supported that movement, though they haven’t removed the need for careful appraisal and transparent communication.