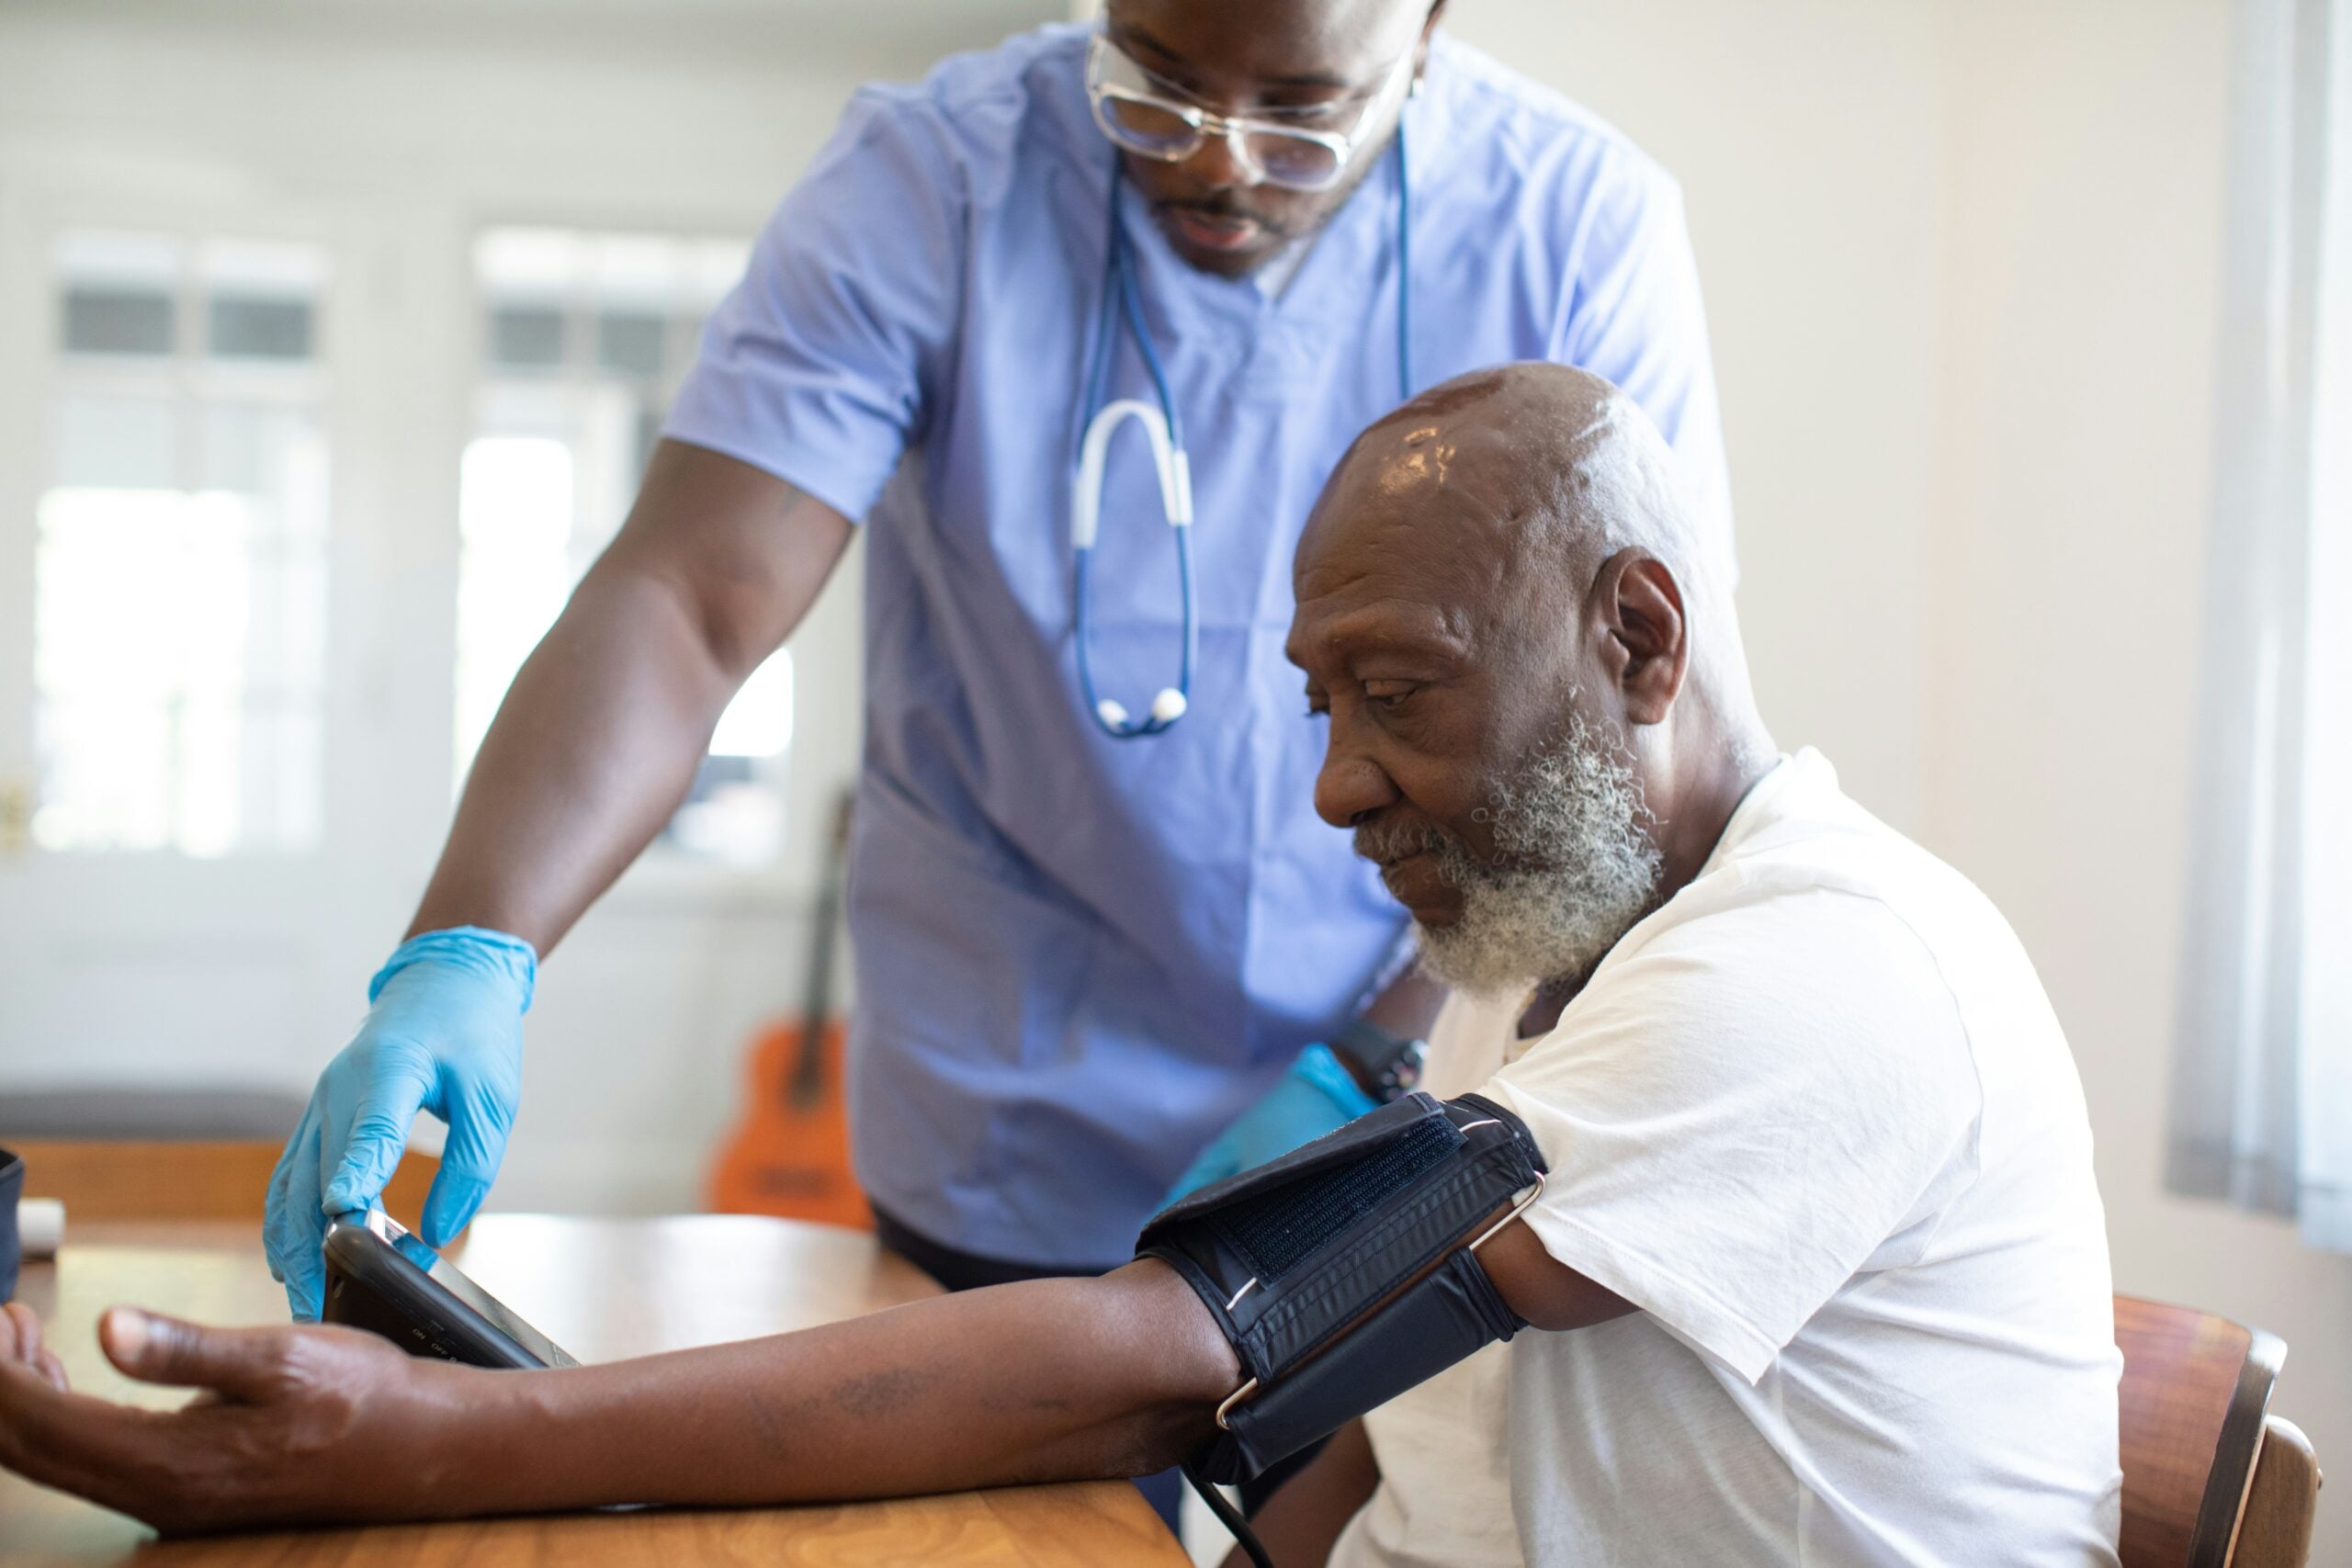
A hospital stay costs more than the bill at the discharge desk. There is the family member who takes leave to stay by the bed, the taxi rides, the meals bought near the hospital and, for many self-employed people, days of lost income. A regular health policy pays for treatment, not for most of this. Hospital cash cover is designed to fill that gap with a fixed amount for every day spent in hospital.
What Hospital Cash Cover Pays
Hospital cash cover pays a set daily amount for each day a person is admitted, regardless of the actual medical bill. If the policy promises ₹2,000 a day and the stay lasts five days, the payout is calculated on those five days alone. Because it is a fixed benefit, the money can be spent on anything the family needs.
Why a Fixed Daily Amount Helps
Some costs stay with the patient even under a well-chosen health plan. A share of the bill may fall on the family because of how the policy is structured, and items such as gloves, masks and other non-medical consumables are often left out of the claim altogether. Beyond the hospital itself, there is travel for relatives, a place for an attendant to stay and paid help at home while a parent is admitted.
For salaried employees with paid sick leave, these costs are usually manageable. For self-employed professionals, small traders and gig workers, a week in hospital can also mean a week without income. A daily cash amount gives them predictable support during that period.
How a Claim Is Calculated
Understanding how hospital cash insurance pays out starts with three numbers: the daily amount, the minimum length of stay and the maximum days covered. Most plans require an admission of at least 24 hours, and some do not pay for the first day or two of each stay. Many also pay a higher amount for days spent in intensive care.
Take a plan paying ₹2,000 a day that excludes the first day of each admission. A six-day stay would pay ₹10,000, whether the bill came to ₹40,000 or ₹4 lakh. Some plans also pay a one-time convalescence amount after an extended stay, which helps with recovery at home. The money is paid to the policyholder rather than the hospital, usually after discharge once the documents are submitted.
Limits and Exclusions
Hospital cash cover carries conditions similar to other health plans. An initial waiting period usually applies for illnesses, though accidents are typically covered from the start. Pre-existing conditions are covered only after their waiting period, and day-care procedures that do not need a full admission are usually excluded.
The numbers vary by plan, but daily benefits commonly range from around ₹500 to ₹5,000, and payouts are often capped at somewhere between 30 and 60 days a year, with a separate limit per admission. Entry ages also matter, since many plans accept new applicants only up to a set age, often around 65. Claims generally need the discharge summary and hospital records showing the dates of admission and discharge, and the policy wording lists the exact caps and documents.
Who Gains Most From It
The cover suits people whose costs during a hospital stay go well beyond the medical bill. That includes self-employed people and others without paid leave, families who would need someone to travel and stay with an older relative, and policyholders whose main plan leaves a meaningful share of each bill with them. It can also suit families who chose a higher deductible on their main plan to keep premiums down. For a salaried person with generous employer cover and paid sick leave, the extra premium may add less value.
Hospital Cash Versus a Regular Health Policy
A best health insurance reimburses actual treatment costs up to the sum insured, while hospital cash pays a fixed sum per day. Because it is a benefit payment rather than a reimbursement, it can usually be claimed alongside a regular health claim for the same admission, and the two do not reduce each other.
That also means hospital cash cannot replace a proper health policy. A daily amount of a few thousand rupees will not pay for surgery or intensive care, so it works best on top of a family health insurance plan sized for major treatment, rather than as a substitute for one.
Choosing the Right Format and Daily Amount
Hospital cash insurance is offered both as a standalone policy and as an optional add-on to a health plan. An add-on is usually simpler to manage, since claims run through the same insurer, while a standalone policy stays in place even if the main health cover is changed later.
A sensible starting point for the daily amount is to estimate what a day in hospital costs the household outside the medical bill: lost earnings, travel, food and any help hired at home. A figure close to that keeps the cover useful without paying for more than the family needs. Alongside a solid health policy, it eases the pressure on the household budget during an unplanned stay.