For NRIs, choosing term insurance involves more than comparing premiums. Financial commitments in India, family responsibilities, country of residence, and long-term goals can all influence the type of cover you may need. The types of term insurance available in India offer different coverage structures for varying financial needs. Understanding these options helps you compare features, policy terms, eligibility requirements, and suitability before choosing protection that supports your family’s financial security and long-term goals.
Types of Term Insurance Available to NRIs
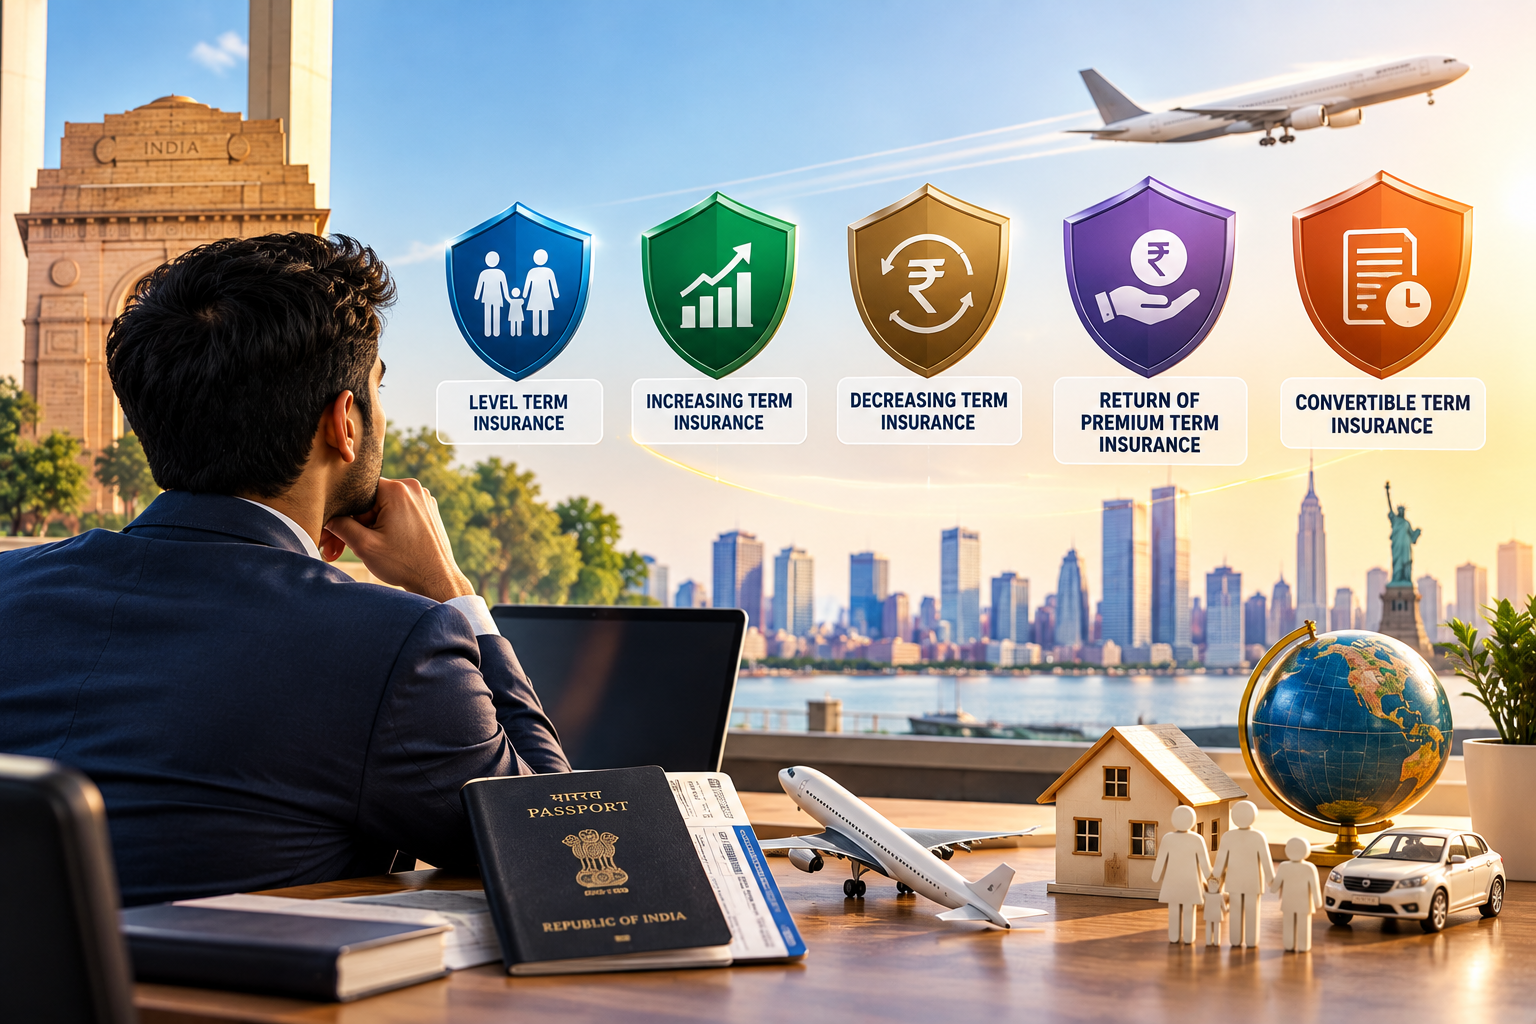
Term insurance can be structured differently depending on the policy and insurer. NRIs can compare the following options, subject to the availability and eligibility requirements of the selected insurer:
Level Term Insurance
A level term plan provides a fixed sum assured throughout the policy term, provided the policy remains in force. It may suit NRIs seeking consistent financial protection for their dependants.
Increasing Term Insurance
An increasing term plan provides a sum assured that increases according to a predefined structure during the policy term. It may suit NRIs whose financial responsibilities are expected to increase over time.
Decreasing Term Insurance
A decreasing term plan provides a sum assured that reduces according to a predefined schedule. It may suit individuals seeking cover that corresponds with declining liabilities, such as certain loan obligations.
Return of Premium Term Insurance
A return of premium (TROP) plan provides a maturity benefit by returning eligible premiums when the policyholder survives the policy term, subject to the policy terms and conditions. It may suit those who prefer a survival benefit along with life cover.
Convertible Term Insurance
Some term insurance policies offer a conversion option that lets policyholders convert existing cover into another eligible life insurance plan during a specified period. This option is available only under certain policies and is subject to the insurer’s terms and conditions. For NRIs, its availability may also depend on the country of residence, underwriting requirements, and other eligibility criteria.
Which Type of Term Insurance May Suit Different NRI Needs?
Every NRI has different financial responsibilities and future goals. The most suitable option depends on individual circumstances. Some common situations are:
- Young Professionals: Level term insurance may provide stable financial protection during the early earning years.
- Home Loan Borrowers: Decreasing term insurance may suit those who want cover linked to reducing loan obligations.
- Growing Families: Increasing term insurance may help address rising financial responsibilities over time.
- Individuals Seeking Premium Return: Return of premium plans may appeal to those who want eligible premiums back if they survive the policy term.
- People Considering Future Changes: Individuals who want flexibility to modify their protection may explore policies offering conversion or other life-stage options, where available.
When choosing term insurance for NRI in India, consider your personal financial goals, family needs, and long-term responsibilities.
Key Factors to Consider Before Choosing a Term Insurance Plan
NRIs should consider the following before making a decision:
- Sum Assured: Choose coverage that supports your family’s future needs and existing liabilities.
- Policy Term: Select a duration that covers your earning years and major financial commitments.
- Premium Affordability: Ensure premiums remain manageable throughout the policy term.
- Eligibility Requirements: Check requirements relating to age, country of residence, documentation, and underwriting.
- Medical Assessment: Medical tests may be required based on age, health, sum assured, and underwriting requirements.
- Optional Riders: Additional riders may provide extra protection for specific situations at an additional cost.
- Claim Settlement Record: Review claim settlement information alongside policy terms and service standards.
- Currency and Payment Considerations: Consider your income currency, financial commitments, and available premium payment options.
These factors can help you choose a policy that suits your present and future financial needs.
How NRIs Can Buy Term Insurance in India
NRIs can generally apply for term insurance from India by completing the insurer’s eligibility, documentation, underwriting, and payment requirements.
- Check Eligibility: Confirm your eligibility based on age, NRI status, country of residence, and underwriting requirements.
- Choose a Suitable Plan: Compare plans based on coverage, policy term, affordability, and features.
- Complete the Application: Provide accurate personal, financial, occupational, and nominee details.
- Submit Required Documents: Provide your passport, visa or residency proof, address proof, income documents, and other requested records.
- Complete Medical Tests: Undergo medical examinations in India or abroad if required.
- Pay the Premium and Complete Issuance: Pay the premium using an available payment method. The insurer can then issue the policy after verification.
When choosing a plan, NRIs can compare options from insurers such as Aviva India and review the available coverage, eligibility requirements, policy terms, and premium payment options. This helps them decide whether the policy suits their needs before starting the application process.
Conclusion
Choosing the right term insurance plan depends on your financial responsibilities, family needs, and long-term goals. Level term insurance may suit those seeking consistent cover, while increasing or decreasing options may suit specific changing financial needs. Return of premium plans may appeal to those seeking a maturity benefit, subject to policy terms. NRIs should also consider eligibility, country of residence, medical requirements, affordability, and policy conditions before choosing a plan. Comparing these factors can help you select suitable financial protection for your family.