A Loan Against Property (LAP) can help you access funds for personal or business needs by using your property as security. Since the loan involves regular repayments over a fixed period, it is important to understand what the monthly commitment may look like before you apply. An EMI Calculator for LAP makes this easier by showing how the loan amount, interest rate, and tenure can affect your EMI. You can adjust these details, compare different repayment options, and choose a loan structure that fits comfortably within your monthly budget and financial plans.
What Is an EMI Calculator for LAP?
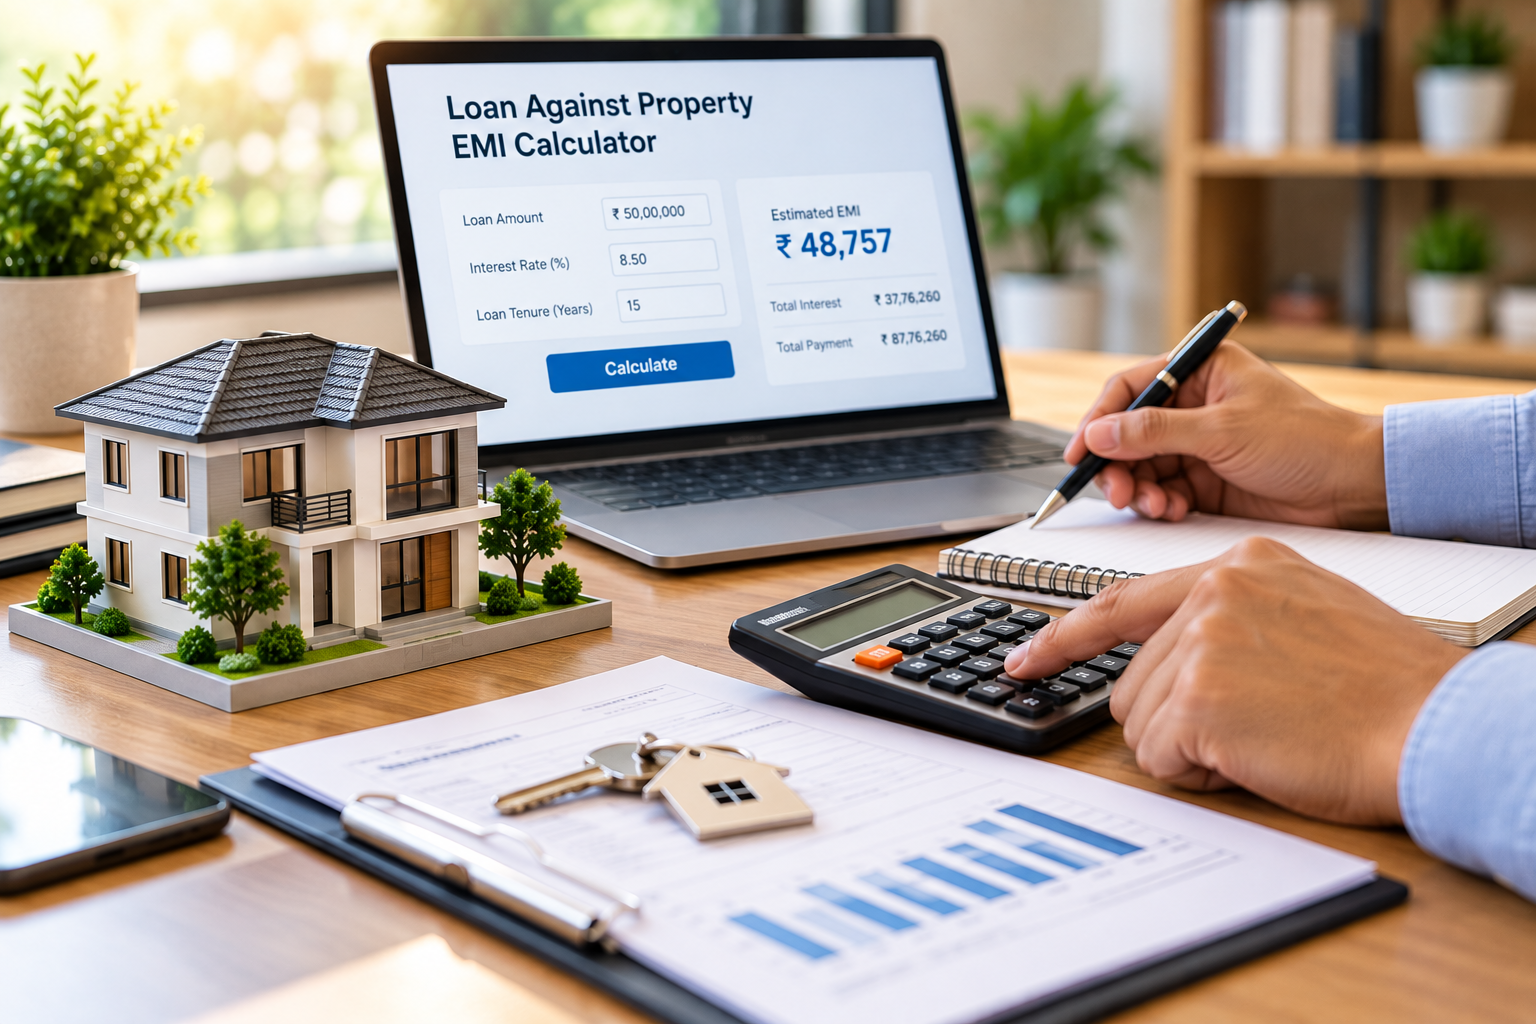
An EMI calculator for LAP is a digital tool that estimates the monthly installment payable on a loan. It requires three key inputs:
- Loan amount
- Interest rate
- Loan tenure
Once you enter these details, the calculator estimates your monthly EMI and may also show the total interest payable and overall repayment amount. For example, lenders such as Tata Capital’s Loan Against Property EMI Calculator help borrowers compare different loan amounts, interest rates, and repayment tenures to understand how these factors may affect their monthly repayment.
Why Use an EMI Calculator Before Taking a LAP?
Taking a loan against property involves a long-term financial commitment. A calculator can give a clearer picture of your repayment obligation before you submit your application. Here are some ways it can help.
1. Estimate Your Monthly EMI
An EMI calculator gives you an estimate of the monthly repayment for your loan. Knowing this amount beforehand helps you compare the EMI with your income, existing EMIs, and regular expenses. This can help you assess whether the proposed loan amount is affordable and fits comfortably within your budget. Loan eligibility alone should not determine how much you borrow. Consider your repayment capacity and choose an amount that you can manage without putting unnecessary pressure on your finances.
2. Compare Different Loan Amounts
The amount you are eligible to borrow may be higher than what you actually need. An EMI calculator lets you compare different loan amounts and see how each one affects your monthly repayment. For instance, you can compare the estimated EMI for ₹20 lakh, ₹30 lakh, and ₹40 lakh. This can help you choose an amount that meets your financial requirement while keeping the EMI manageable. Borrowing only what you need can also help limit your overall repayment and interest cost.
3. Understand the Impact of the Loan Against Property Interest Rate
The loan against property interest rate directly affects your EMI and total interest payable. If the loan amount and tenure remain the same, a higher interest rate generally means a higher EMI and greater overall interest cost.
The rate offered may depend on factors such as your credit profile, income, property details, loan amount, and lender-specific criteria. Use an EMI calculator to compare different rate scenarios and understand how they may change your repayment.
4. Compare Different Tenures
The tenure you choose affects both your monthly EMI and the total loan cost. A longer tenure can lower the EMI by spreading repayments over more months, but it may increase the total interest payable.
A shorter tenure usually means a higher EMI but can reduce the overall interest cost. Compare different tenures, such as 10, 15, and 20 years, using an EMI calculator to balance monthly affordability and total repayment.
5. Plan Your Monthly Cash Flow
Your EMI should fit comfortably within your overall monthly budget. Before deciding how much to borrow, consider your regular expenses, existing EMIs, insurance premiums, investments, and other financial commitments.
An EMI calculator can help you assess different loan amounts and tenures against your available monthly surplus. This can help you choose a repayment plan that meets your funding needs without putting unnecessary pressure on your finances.
How to Use an EMI Calculator for LAP
Using an EMI calculator is simple and can help you compare repayment options before applying for a Loan Against Property.
Step 1: Enter the loan amount
Enter the amount you plan to borrow.
Step 2: Enter the interest rate
Add the applicable loan against property interest rate. If the final rate is not confirmed, try different rates to see how they affect the EMI.
Step 3: Select the loan tenure
Choose the repayment period you are considering.
Step 4: Check the estimated EMI
The calculator will show the estimated monthly installment based on the details entered.
Step 5: Compare different scenarios
Change the loan amount, interest rate, or tenure to compare different repayment options and identify a combination that fits your budget.
This can help you understand the potential repayment obligation and plan your borrowing more effectively.
What Else Should You Consider Besides EMI?
An EMI is only one part of the borrowing cost. Before choosing a Loan Against Property, consider the total interest, fees, property valuation, and repayment terms.
Total Interest Payable
A lower EMI does not necessarily mean a lower overall borrowing cost. A longer tenure may reduce the monthly payment but increase the total interest payable.
Processing Fees and Other Charges
Review applicable processing fees, documentation charges, and other costs associated with the loan. These can add to the overall cost of borrowing.
Property Assessment
Since a LAP is secured against property, the property’s value, type, location, and documentation can affect the lending assessment.
Loan-to-Value Position
The loan amount may depend partly on the property’s value and applicable lending criteria. Therefore, the amount you want to borrow may differ from the amount you are eligible to receive.
Repayment Flexibility
Review the terms for part-prepayment, foreclosure, and other repayment options before finalizing the loan.
Final Thoughts
An EMI calculator can help you understand the potential monthly repayment before taking a Loan Against Property. By comparing different loan amounts, interest rates, and tenures, you can choose an option that fits your budget and financial commitments. However, EMI is only one part of the borrowing cost. Before deciding, consider total interest, applicable charges, property valuation, loan-to-value position, and repayment terms. Reviewing these factors together can help you plan your LAP more carefully and choose a repayment structure that you can manage comfortably over the loan tenure.