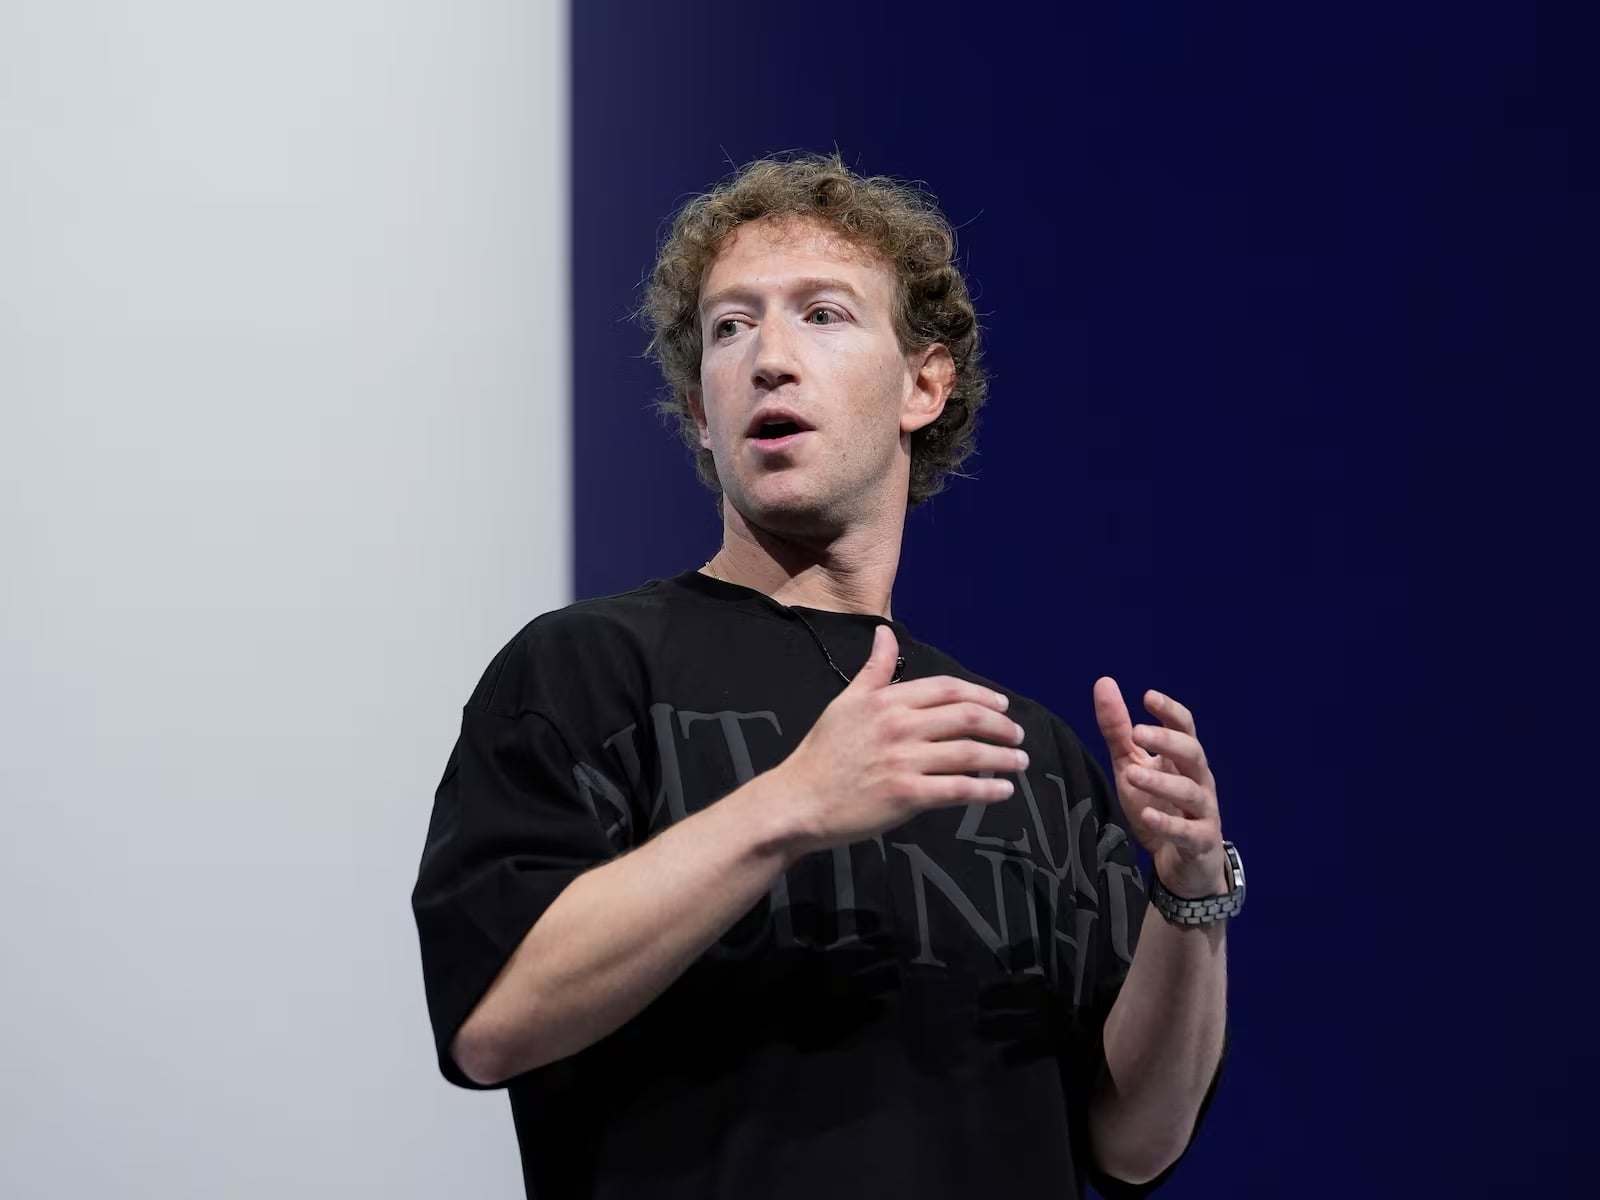
Meta CEO Mark Zuckerberg reportedly considered leaving California over a proposed billionaire wealth tax that could expose him to a multibillion-dollar payment. The social media company’s response was to develop a financial incentive designed to keep its chief executive near Silicon Valley while helping him manage the potential tax burden without immediately sacrificing his voting control over the company.
The situation highlights the growing tension between tax policies targeting the wealthiest individuals and the interests of technology companies seeking to retain their top executives. For Meta, keeping Zuckerberg close to its headquarters is particularly important as the company increases investments in artificial intelligence and competes with other major technology firms.
The proposed arrangement also demonstrates how concerns about personal taxation can influence corporate compensation, executive retention and shareholder structures at some of the world’s largest companies.
Proposed Wealth Tax Could Cost Zuckerberg Billions
California’s proposed billionaire wealth tax has raised concerns among some of the state’s wealthiest residents. Unlike conventional income taxes, which apply to earnings, a wealth tax targets accumulated assets, including investments and company shares.
Zuckerberg’s fortune is largely tied to his ownership of Meta, making him potentially vulnerable to a substantial tax bill if the proposal becomes law and applies to his holdings. With his net worth estimated at hundreds of billions of dollars, even a relatively small percentage-based levy could translate into billions of dollars in additional costs.
For wealthy technology executives, paying such a bill can present a particular challenge. Much of their wealth exists on paper through shares rather than cash readily available in bank accounts. Meeting a large tax obligation could therefore require selling investments, borrowing against assets or finding alternative sources of liquidity.
Selling a significant number of shares could also affect Zuckerberg’s influence over Meta. The company’s share structure gives him considerable voting power, allowing him to maintain control over corporate decisions despite owning less than a majority of its overall economic interests.
These considerations reportedly prompted Zuckerberg to explore relocating his primary residence outside California before the proposed tax could take effect.
Meta Develops an Incentive to Retain Its CEO
Meta responded by considering a financial arrangement intended to address Zuckerberg’s potential tax exposure while encouraging him to remain near the company’s headquarters.
The proposed structure involves issuing non-voting Class C shares that could provide Zuckerberg with additional liquidity. Because these shares would not carry the same voting rights as his existing holdings, they could allow him to raise funds without immediately surrendering his influence over the company.
The arrangement is designed to balance two competing priorities: giving Zuckerberg greater financial flexibility and protecting Meta’s existing leadership structure.
The proposed agreement also links the financial incentive to his continued service. Restrictions on selling certain shares would encourage him to remain actively involved in the company rather than treating the arrangement as an unconditional financial benefit.
Under the reported terms, Zuckerberg would commit to remaining in California, or another jurisdiction where Meta maintains its headquarters, for eight years, subject to provisions addressing unforeseen circumstances. He would also be expected to continue serving in a full-time leadership role.
For Meta, the arrangement represents an effort to prevent a potential relocation from disrupting its long-term strategy.
Artificial Intelligence Raises the Stakes
The timing of the reported agreement is significant because Meta is investing heavily in artificial intelligence. The company is competing to develop advanced AI models, expand computing infrastructure and attract specialised researchers and engineers.
Zuckerberg has played a central role in determining Meta’s strategic direction, including its investments in AI and its broader technology ambitions. His continued involvement is therefore important to the company’s efforts to compete with rivals developing increasingly sophisticated AI systems.
Meta’s leadership reportedly views having Zuckerberg close to its Silicon Valley operations as valuable for coordination and decision-making. The company has also faced challenges associated with remote working arrangements, strengthening the argument for maintaining direct executive involvement at its headquarters.
A relocation could potentially introduce additional complications in managing major projects and coordinating with senior leadership. Although modern communication tools allow executives to work across locations, Meta appears to consider Zuckerberg’s physical proximity an advantage.
The financial incentive can consequently be viewed as more than a response to a personal tax concern. It also reflects the company’s willingness to structure compensation around retaining an executive it considers essential to its long-term plans.
California’s Tax Debate Intensifies
The proposed wealth tax has intensified the debate over whether taxing accumulated billionaire wealth can generate public revenue without encouraging wealthy residents to leave the state.
Supporters argue that a levy on the fortunes of the richest individuals could help finance public services, healthcare and social programmes. They contend that individuals who have benefited substantially from the state’s economy should contribute more toward its public finances.
Critics, however, warn that wealthy residents could relocate, restructure their investments or pursue legal challenges to limit their exposure. Such responses could complicate implementation and potentially reduce the revenue generated by the measure.
Zuckerberg’s reported consideration of leaving California illustrates the challenge facing policymakers. The state remains a major centre for technology companies, investors and entrepreneurs, but taxation can influence where wealthy individuals choose to establish their primary residences.
The final impact would depend on the proposal’s implementation, eligibility rules and any subsequent legal or administrative developments.
What the Arrangement Means for Meta
Meta’s response underscores the growing connection between executive compensation and public policy. A proposed tax measure affecting one individual has prompted the company to consider changes involving shares, liquidity and long-term leadership commitments.
For shareholders, the arrangement raises questions about the cost of retaining a chief executive and the role of corporate incentives in protecting strategic continuity. For Zuckerberg, it could provide a way to manage a potential financial liability while maintaining his voting influence.
Ultimately, the episode highlights the competing interests of governments seeking additional tax revenue and companies seeking to preserve executive stability.
Whether Meta’s proposed arrangement proves necessary will depend on the future of California’s wealth tax proposal. Nevertheless, the situation demonstrates how taxation can influence decisions extending beyond personal finances, potentially affecting corporate governance, executive retention and the strategic direction of major technology companies.